


This is the final episode in our 3-part series exploring how agentic AI will transform primary care. In this final episode, we showcase the pioneers already building towards this future in the AI x Primary Care market map.

With this market map we showcase the companies pioneering the future of primary care. All 430 companies are European born, have raised >$1mn and sit in one of the five areas where we believe technology is rebuilding everyday care. See part 1 and part 2 to dive into our vision for the future of primary care.
Just last week we hosted our annual HealthTech Summit, where we gathered an outstanding room of the obsessive founders building a better healthcare system. We heard from European health champions AMBOSS, Doctolib, Oviva, Avelios and many more, and the room was bursting with ambition to build global health champions out of Europe.
It’s time to build!
The Pioneers re-building Primary Care
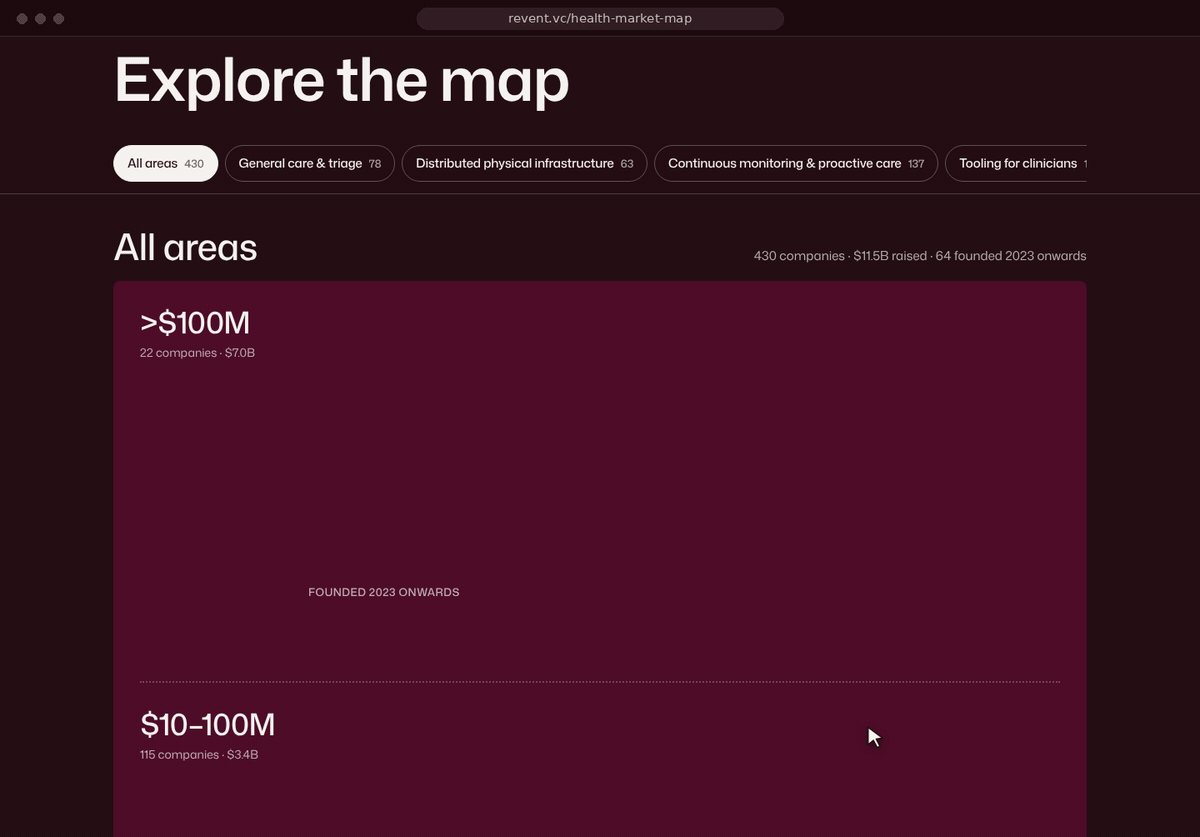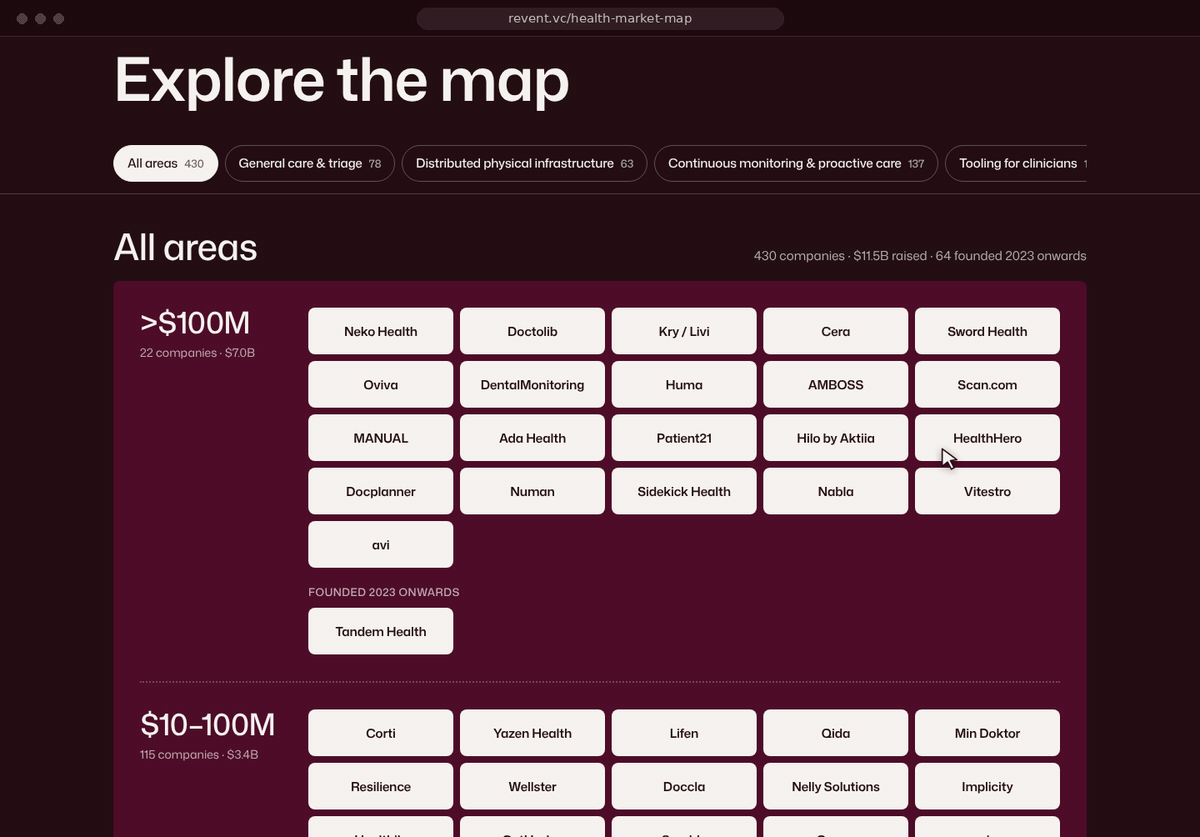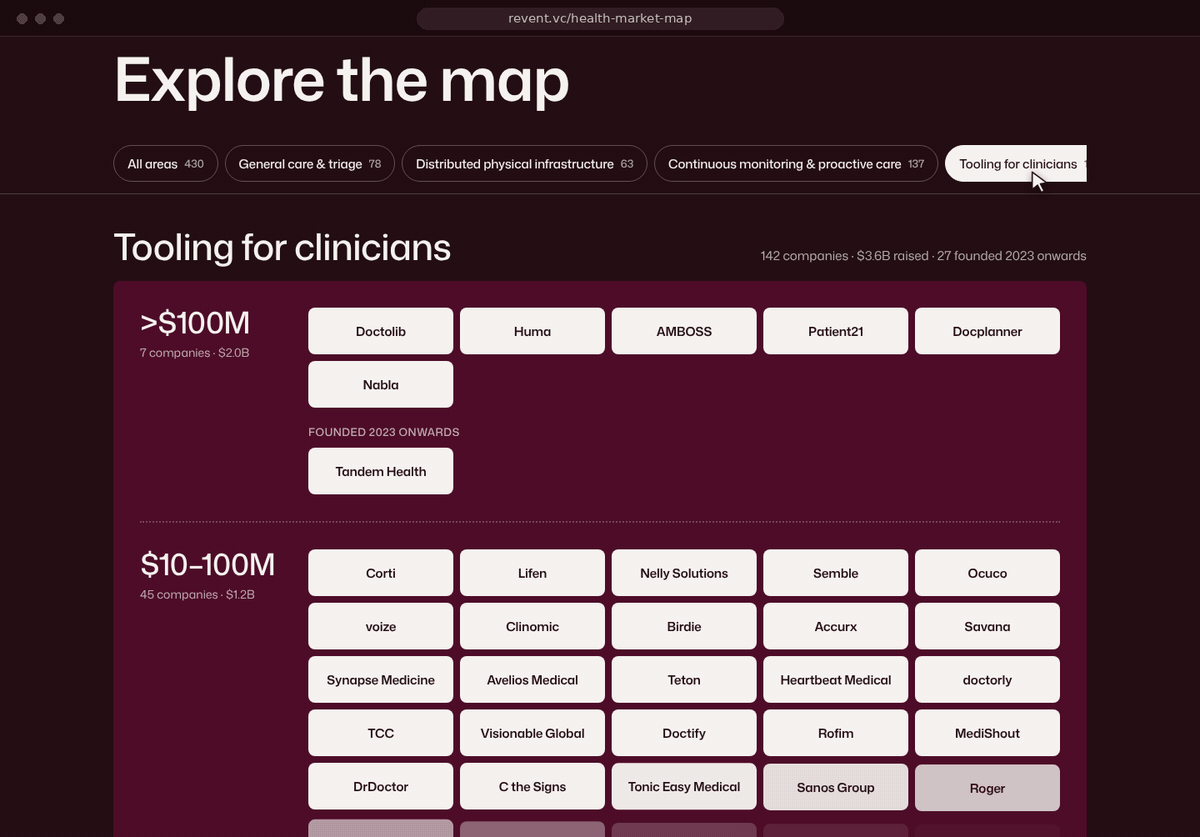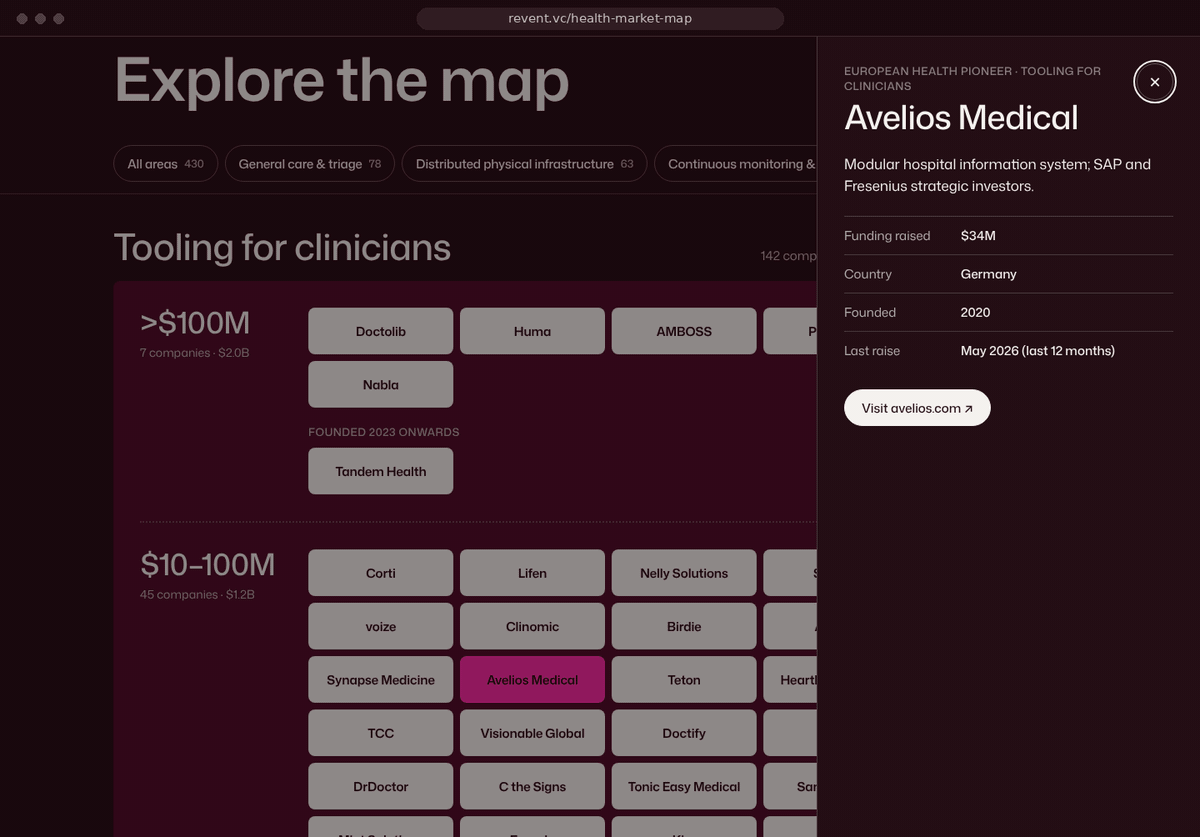
We are seeing some incredible companies being built across the five key domains where we see AI transforming primary care.
We signalled some of the US early movers in parts 1 and 2 that we can learn from, such as Doctronic and Counsel Health. However, Europe has its own pioneers too, from Avelios rebuilding the hospital operating system to Neko turning the health check into something people queue for, and behind them a new generation of companies.
One major shift we are seeing right now, is a new breed of consumer health companies. They promise to house your personal health record, offer regular low-friction blood tests, ongoing monitoring through wearables and 24/7 access to an AI doctor which you can upgrade to a facetime with a real one. In essence, the consolidation of your primary health experience into one super app. Some early examples are Calibre, Superpower and Octo Health.
It might sound familiar, these things have been promised before. But we believe we are now over the threshold where AI is both performant and starting to become trusted by the system (e.g. Doctronic’s approval to autonomously renew prescriptions).
This is a patient experience we have desired for decades: a healthcare system that knows who I am, prompts my behaviour, keeps me in the know on the state of my symptoms and takes responsibility for ensuring I’m seen in time!
We also expect to see the big wearables platforms (e.g. Apple, Oura, Fitbit) seek to expand their footprint in this direction, capitalising on their incredible distribution power. As well as the companies betting on in-person clinics (e.g. Neko, Curitt), who will expand their footprint from physical only, to an all-encompassing digital home for your health. This is a new distributed healthcare system.
The AI-natives
64 companies on the map were founded in 2023 or later. They have never known a world without ChatGPT, and for them they are able to build their company as an AI-native from day one. This is a genuine advantage!
Where they’re choosing to build is telling. Almost 70% are in tooling for clinicians or general care and triage, against roughly half of the full map. Scribes, AI receptionists, voice agents, billing and coding. It seems that the AI-natives are attacking the admin layer first, where a model can take work off a GP’s desk on day one. Vocca is a good example: founded in 2024, it has already raised $26M for AI voice agents that answer the phone and book appointments for medical practices.
Continuous monitoring tells the opposite story. It makes up a third of the map, but only 11% of the AI-natives. Hardware, trials and regulation still keep new entrants out.
At least 166 companies have raised in the last 12 months, which is a mix of these young AI-native companies and big platforms like Doctolib, Neko and Avelios.
Building a global major from Europe
To date, we have seen US health companies raise significantly more capital than their European counterparts. This is of course partly a function of the US market being a lot bigger. It’s also because scaling across a continent of different payer systems is genuinely hard.
However, the prize for the companies that do crack it is enormous: a recession-proof market of unmatched scale, with incumbents running on decades-old technology, and almost no one at the top of the funding table yet.
We keep saying that it’s not rocket-science to imagine a better healthcare system, it’s a system that’s seen little change in decades. But the reason we haven’t yet seen huge companies being built in this space, is largely due to wrong incentive schemes, high inefficiencies due to the public market nature of most European healthcare system as well as a highly fragmented and regulated market mainly controlled by technology adverse doctors who are the gatekeepers to most innovation.
We are fully convinced that some of Europe’s biggest start-ups of the coming decades will be solving problems in healthcare. A system unparalleled in scale, and so neglected from the technology revolutions of the past and (so far) the present.
We are in a unique moment - it’s time to build!

If you share our belief that the game has changed and are obsessing about where AI can transform primary care, we would love to speak with you!